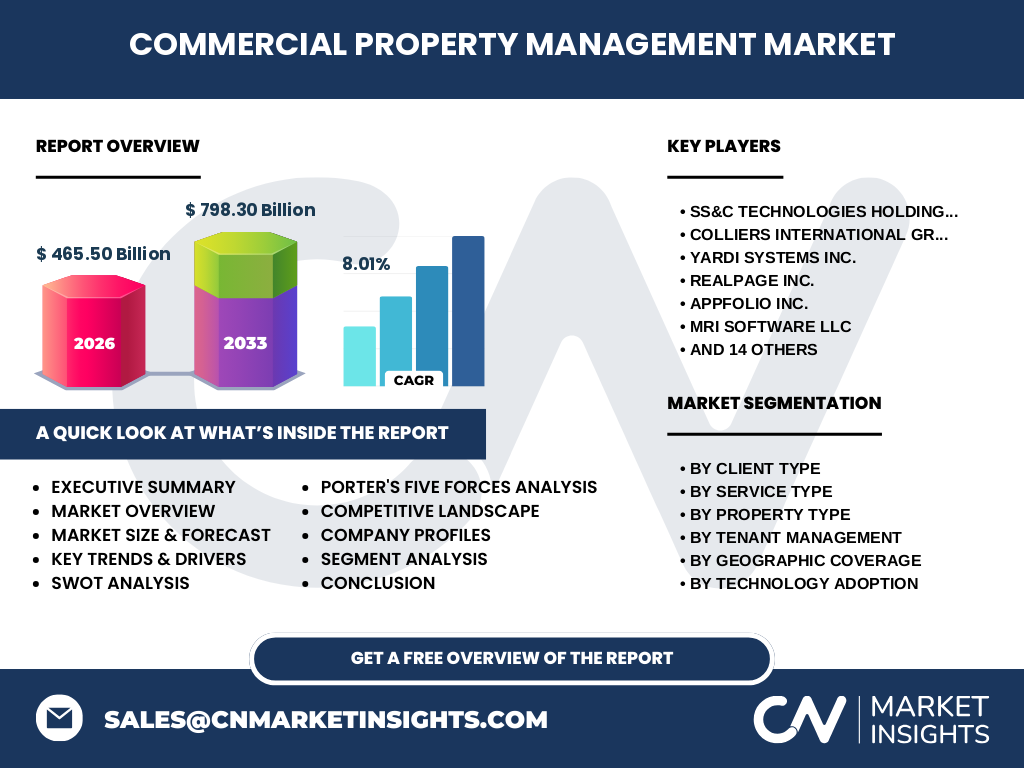
Market overview of the Commercial Property Management Market
Our analysis indicates that the Commercial Property Management Market size stands at $465.50 Billion in 2026. This sector encompasses operational oversight of office buildings, retail spaces, and mixed-use developments, driving economic efficiency across urban and suburban commercial real estate portfolios.
What are the primary drivers and restraints shaping the industry?
Market expansion is propelled by rising urbanization and complex regulatory compliance mandates. Conversely, elevated borrowing costs and supply chain delays for HVAC and building maintenance raw materials act as primary restraints, squeezing profit margins for institutional asset owners.
Structural Growth Trends in Commercial Property Management
The data suggests a rapid pivot toward cloud-based property management solutions and IoT-enabled facilities management. Firms like Yardi Systems Inc. and MRI Software LLC are leading this digital transformation, optimizing lease administration and utility tracking.
How did the COVID-19 pandemic impact sector recovery?
The pandemic forced a structural re-evaluation of indoor air quality and hybrid workplace occupancy management. Recovery has been spearheaded by tech-forward operators implementing contactless tenant communication and robust financial reporting tools to mitigate vacancy risks.
Competitive Benchmarking and Market Concentration
The landscape features a mix of global real estate giants like Colliers International Group Inc. alongside specialized technology providers such as AppFolio Inc. and RealPage Inc. Market concentration is moderate, with enterprise players aggressively acquiring niche proptech platforms.
Executive Summary of Commercial Property Management Industry Trends
Valued at $465.50 Billion in 2026, the Commercial Property Management Market industry trends point toward a high-tech, sustainability-focused future. Investors must prioritize integrated platforms that streamline expense tracking and tenant retention services.
Market forecast from 2027 to 2033
Our research forecasts the market to surge from $465.50 Billion in 2026 to reach $798.30 Billion by 2033. This represents a robust compound annual growth rate (CAGR) of 8.01%, driven by escalating demand for institutional-grade asset optimization.
Segmentation analysis across client, service, and property types
The sector segments across diverse pillars: Client Type (REITs, Institutional Investors), Service Type (Facilities Management, Financial Management), and Property Type (Office Buildings, Mixed-Use Developments). Each segment demands specialized technological interventions for optimal yield generation.
Geographic distribution and regional performance
Geographic coverage spans dense urban areas, expanding suburban nodes, and international markets. Urban centers currently dominate revenue generation due to high concentrations of premium office buildings and complex mixed-use developments requiring rigorous security and cleaning services.
In-depth regional market review
North America leads adoption of integrated property management systems, whereas Asia-Pacific exhibits the fastest regional growth rate, fueled by rapid urbanization and massive commercial construction pipelines requiring advanced lease administration and tenant retention services.
Strategic positioning of leading company profiles
Industry leaders like SS&C Technologies Holdings Inc. and Altus Group Limited leverage proprietary analytics for precise tax management and budget planning. Meanwhile, DoorLoop Inc. and TenantCloud Inc. capture the SMB property owner segment.
Porter's Five Forces analysis of competitive intensity
Bargaining power of buyers is moderate to high, tempered by proprietary software switching costs. Threat of new entrants remains constrained by high initial R&D investments required to build secure, compliant cloud-based property management solutions.
SWOT analysis of the commercial asset management sector
Key strengths include recurring revenue models, while weaknesses involve vulnerability to macroeconomic interest rate shifts. Opportunities lie in automated rent collection, whereas threats stem from escalating cybersecurity risks within cloud databases.
Value chain analysis from raw materials to end-users
The value chain flows from raw building materials and IoT hardware manufacturers through software developers like Spacewell International NV and Aareon AG, ultimately delivering streamlined operational value to corporate tenants and institutional investors.
Investment insights and high-potential areas
Strategic analysis highlights cloud-based financial reporting and automated expense tracking as high-ROI investment areas. Investors should target proptech innovators offering seamless API integrations for commercial portfolio scaling.
Conclusion and key takeaways for stakeholders
Reaching $798.30 Billion by 2033 at an 8.01% CAGR, the market rewards operational agility. Stakeholders must embrace automated tenant communication and advanced facilities management to secure long-term market share.
Research methodology for baseline estimates
Our baseline estimates are rigorously triangulated by combining trade registry data, primary stakeholder interviews with enterprise executives, and secondary macroeconomic indicators regarding commercial real estate absorption rates and proptech funding rounds.
Scope of the report and coverage parameters
This report covers global commercial property management dynamics across urban, suburban, and international markets. Limitations exclude residential-only single-family portfolios, focusing strictly on income-generating commercial, retail, and mixed-use assets.
Recent developments in the proptech and management ecosystem
Recent market announcements highlight aggressive M&A activity and strategic partnerships among firms like Buildium LLC and Property Matrix Inc., focusing on the integration of AI-driven complaint resolution and automated tax management modules.